Do we know the “Web of Death Care”?
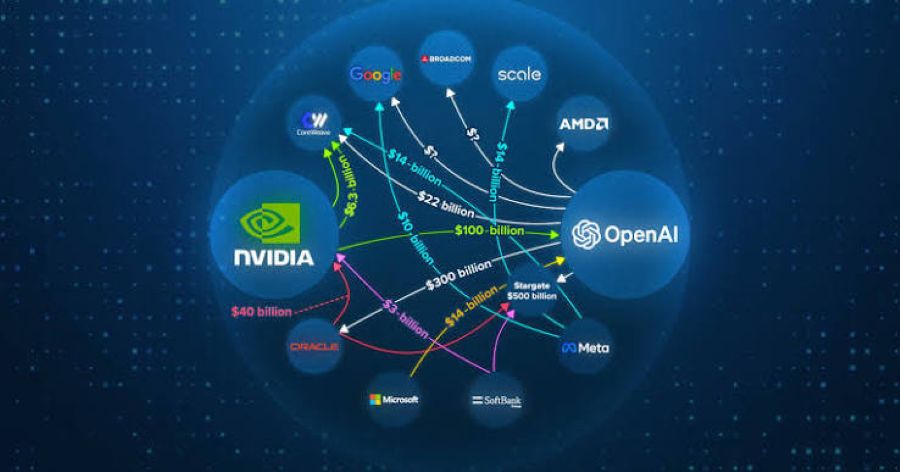
My mind was somewhat “boggled” the other day when I saw an intricate graph-form portrayal about how the companies involved in computer chip, artificial inteligence, and other technological systems are so interelated with loan agreements, purchase agreements, and in some cases, equity ownership.
For instance, I’m a stockholder in the company Broadcom. If you read about Broadcom you will see that the company is rapidly increasing the sale of its chips. However, if you read further you will also notice that Broadcom is financing some of that growth themselves by borrowing money to some of the companies that buy its chips.
Most of us would assume that the chip maker companies like Broadcom do this borrowing in order to build their sales numbers.
At some point in time that “chip purchasing company” could put a company like Broadcom in a precarious position. Let’s just say the company buying the Broadcom chips has a slowdown in business which not only slows the Broadcom sales growth but because they are indebted to Broadcom this hypothetical slowdown of “the purchasing company’s products” would probably cause problems for Broadcom in collecting on the debt owned them because of the cash-flow problems of the debtor. . . . It’s almost like “carrying an account”, but with numbers with many zeroes behind the debt balances and much bigger stakes for the debt holder.
The image that I saw and based this article on is image-protected but I found the image below that in someway shows the “inter-connectedness” of these companies. Seeing it made me think of the “inter-connectedness” of Death Care companies over the years and I just thought I would point out some obvious connections most of you maybe know about and some history on “Death Care inter-connectedness” over the years that some of you probably didn’t know about.
Insurance Company “Inter-connectedness” as Loan Originators. Preneed companies that pull in preneed premium revenue need some place to park those premium dollars so they can grow and pay off future claims in the future. Because of that, and that they know funeral homes and cemeteries because of their existing relationships with them, setting up, and in some cases servicing loans, is one way for them to raise the yield on those preneed premium dollars.
Non-bank loans to funeral home operators for building, acquisition, start-up, and equipment probably was started by Service Corporation International when they opened Provident Services for that purpose in 1988. That company operated as a wholly-owned SCI entity until almost 2000 when SCI made some strategic decisions about divesting non-core assets to focus on funeral services and cemeteries in North America.
By the way, it was about the same time that SCI decided to divest their operations in Great Britain, France, and Germany.. . . . although that process was not finished until 2014. Wikipedia says this about SCI’s divestiture’s from that era, “By eliminating these last European units, SCI successfully reduced its global footprint from an all-time peak of 20+ countries down to a highly streamlined, pure-play North American operator.” . . . .Not everybody in Death Care today knows about that history of SCI which is the only reason I bring it up in this article.
Here’s a couple of your preneed providers that also offer or suggest lending (loan) programs to the profession:
Funeral Directors Life: FDL Mortgage Lending Services
Homesteaders Life Company: Homesteaders Life Financing
Related: “Funeral Directors Life announces a new preneed growth rate increase”. (Released Monday, October 20)
The SCI Casket Story — SCI also entered the casket manufacturing and supply business in 1986. They purchased a company called Amedco, which had earlier acquired what was known as York Casket, in 1986 hoping to not only supply their own funeral homes with caskets, but also supply independent funeral homes with caskets. Apparently, the task of a large funeral home operator supplying caskets to independent operators, some of whom might have been their funeral home competitors, proved difficult.
By 1990, SCI exited the casket business and the spin-off, York Casket, became the York Group and was sold to private investors. That company became a major player in the business and was eventually acquired by Matthews International.

Tom Anderson
Funeral Director Daily
Funeral Director Daily take: I’ve had my take for some time as to the lending business and your funeral home. I think rates may go up more before they come down. If you have adjustable rate loans brace for higher interest payments to come.
And, in simply pointing out the “web of Death Care” that exists, it wouldn’t surprise me that if your preneed provider increases rates on preneed policy growth (such as announced above) then interest rates on the company’s funeral home customer loans may also see an increase.
It’s simple, in a market economy if your preneed provider gives very low rates of interest credit to your existing preneed accounts, those accounts will not keep up with inflationary times and the services and merchandise you provide that consumer family will have compressed margins because the costs incurred in providing that funeral have went up more than the eventual preneed payment. The end result of that, in the long run, is that you will look for another preneed provider — one whose rates follow closer to your inflationary costs. That’s one reason that preneed account growth rates need to be increased at times.
And to pay those increased rates, the preneed provider that also offers loans may have to increase rates on the money they lend to you, if contractually available in your loan documents, to afford the costs of the preneed growth increases. . . . . It can be a wicked circle!!
If that is the case, rates going up, the more places you have to “shop” for interest rates may be of some benefit. I always used local banks because I had great relationships with the bankers and they trusted what I said about my business was the best knowledge that they could ever get on it.
However, if your local bankers don’t understand the cash-flow nature of Death Care, the Preneed companies do. . . . .Don’t underestimate them in helping your business out if you go “shopping”.. . . . . .But, be aware of the “inter-connectedness” of some preneed/loan companies.
More news from the world of Death Care:
- Leaf & Water expands water cremation access the Northeast. Market Insider
- “You’re honoring a life well-lived”: Embalmers describe their work. The Guardian (Great Britain)
- Embalming amendment goes missing: Zoning hearing goes cold. LymeLine (CT)
- Live well: Colorado town has only open-air legal funeral pyre in U.S. The Denver Gazette (CO)
Enter your e-mail below to join the 3,482 others who receive Funeral Director Daily articles daily
“A servant’s attitude guided by Christ leads to a significant life”